



Why Is the Sequence Important in Title Deed Transfer with a Mortgage?
When purchasing a home with a mortgage, the title deed transfer, bank mortgage, and loan disbursement follow a specific sequence. If this order is disrupted, the buyer, seller, and bank can all face issues. Since dozens of mortgage transactions take place in Konya every week, understanding the rules clearly helps avoid wasting time and money.
The bank will not release the loan until a mortgage is registered on the title deed. The Title Deed Office will not complete the transfer until the mortgage is in place. That’s why all steps follow a logical chain.
Step-by-Step Process on Title Deed Day
On title deed day for a mortgaged home purchase, the process follows this order:
- The buyer and seller are present at the Title Deed Office at the scheduled appointment time.
- A debt check (SGK, tax, municipality) is carried out on the seller; if clear, the process continues.
- The title deed transfer contract is read and signed.
- The buyer transfers the remaining sale amount (down payment + costs) to the seller’s account via EFT.
- If the bank representative is present, the mortgage document is signed at the same time.
- The title deed officer processes both the transfer and mortgage in the system simultaneously.
- Once approved, the title deed is registered in the buyer’s name and the bank releases the loan to the seller’s account.
This sequence never changes. Especially in Konya Title Deed Office, where there is high volume, arriving on time for your appointment is critically important.
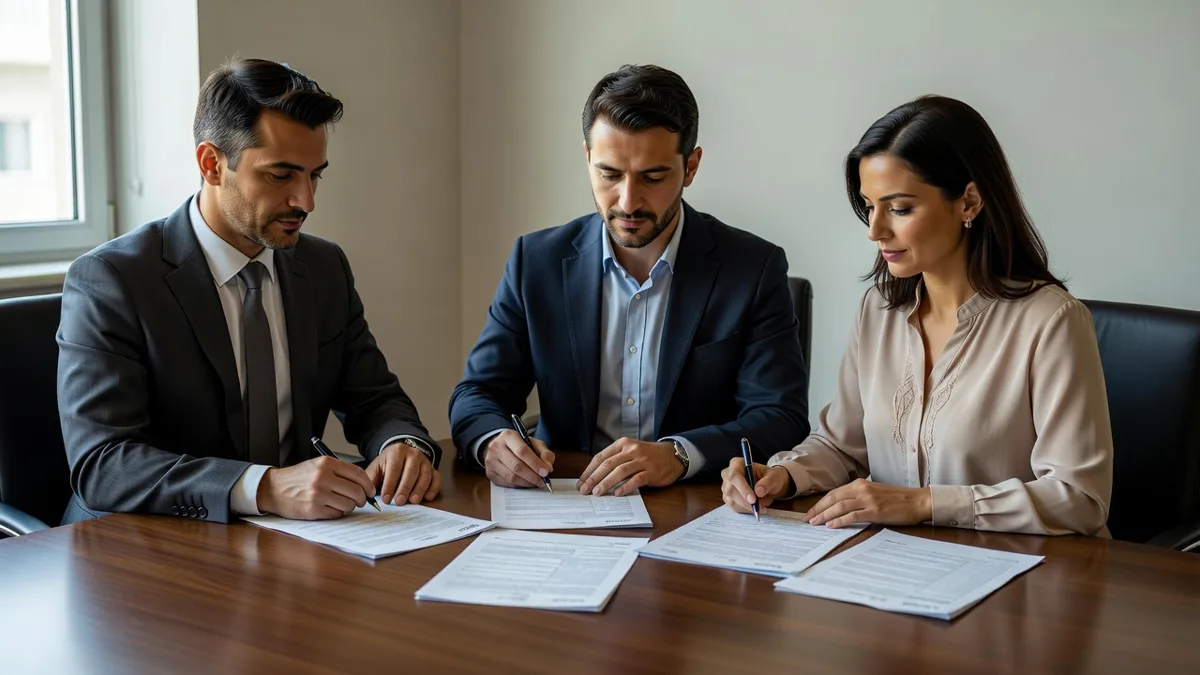
Responsibilities of the Bank, Buyer, and Seller
Each party’s responsibilities are clear:
- Buyer: Have the down payment and all costs ready, and complete all required documents in full.
- Seller: Ensure the title deed has no liens, mortgages, or restrictions.
- Bank: Approve the loan, register the mortgage, and release payment to the seller after transfer.
The bank will not release the loan before the mortgage is registered on the title. This is a BDDK regulation with no exceptions.
4 Common Mistakes in Mortgage Purchases
1. Paying the down payment to the seller in cash before title deed day
2. Sending money to the seller after being told the “loan is approved” but before transfer
3. Not clearly stating in the contract who pays which fees and taxes
4. Failing to account for the risk of the bank representative not showing up, which can delay the process
These mistakes cause financial loss for several buyers in Konya every month.
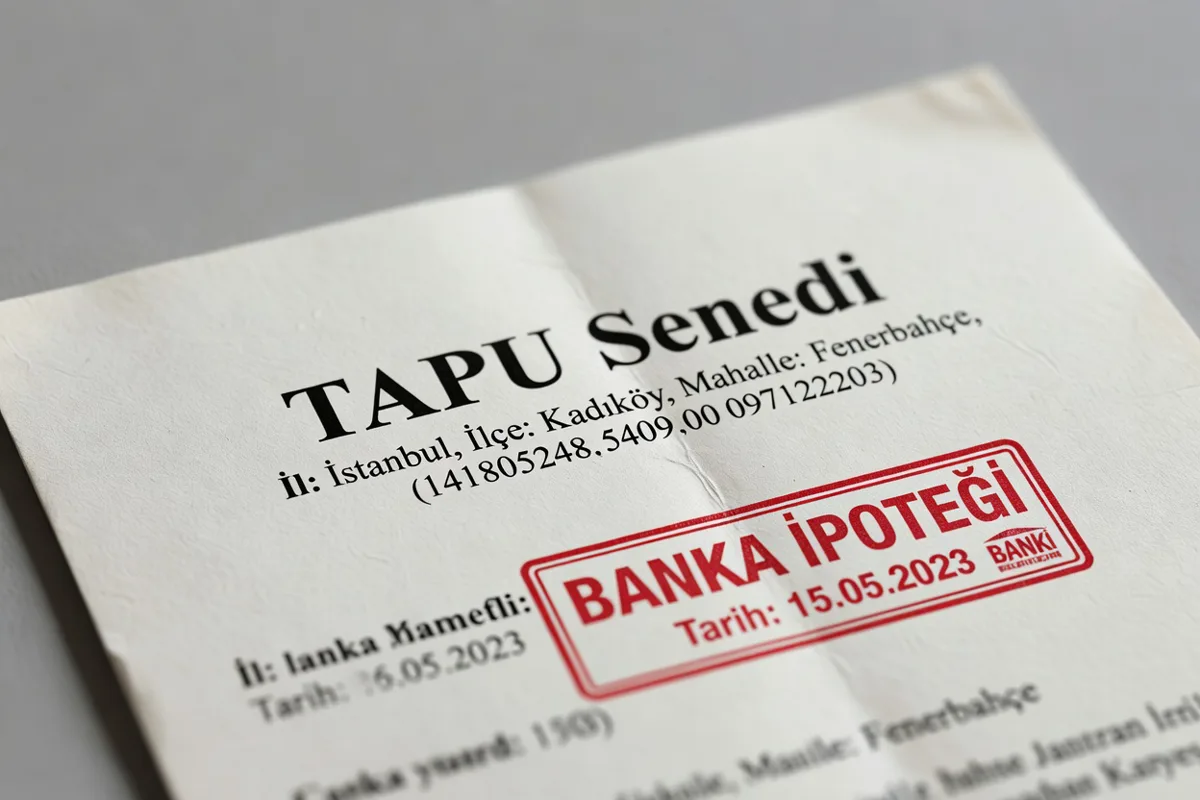
Are the Title Deed Transfer and Mortgage Processed at the Same Time?
Yes. In current practice, the “transfer + mortgage” processes for mortgaged home purchases are completed simultaneously on a single title deed. The title deed officer will not register the mortgage before approving the transfer, nor will they complete the transfer without the mortgage. These two steps are interdependent.
After the transaction, when the buyer receives the title deed, they will see the bank mortgage noted on it. This is normal and remains until the loan is fully paid.
Frequently Asked Questions
Can the title deed be transferred before taking out the loan?
No. Banks will not disburse the loan without a mortgage in place. For this reason, title deed transfer and mortgage registration are carried out on the same day and at the same time. Otherwise, the bank cannot release the funds to the seller.
What happens if the bank representative doesn’t show up on title deed day?
The transaction is usually postponed. Since the appointment time is fixed, the representative’s absence affects both buyer and seller. That’s why we recommend getting written confirmation from your bank for the exact appointment time.
Should the down payment be paid on title deed day or earlier?
The down payment and all costs must be transferred via EFT to the seller’s account on title deed day, in front of the title deed officer. Making cash payments beforehand carries significant risk for the buyer.
If you’re planning to buy a home in Konya with a mortgage, review the entire process step by step with your bank’s mortgage specialist and a trusted real estate consultant before your title deed appointment. Thorough preparation ensures your title deed day goes smoothly.